The Power of Real Estate Co-Investment with a Local Partner
You don't have time to read? Now you can listen.
In real estate investment, capital is essential, but rarely sufficient on its own. The ability to identify strong assets and business opportunities, understand exactly which target audience will best value the specific characteristics of a property, interpret the local context, assess urban planning risks, anticipate licensing challenges, structure the operation and execute the transformation with discipline is often what separates an interesting opportunity from a truly successful investment.
It is in this context that co-investment with an experienced local partner becomes particularly relevant. More than a simple joint participation in a transaction, real estate co-investment represents a way of aligning interests between investors, local partners, owners and experienced operators. When properly structured, it allows risk to be distributed, execution capacity to be strengthened, capital to be brought closer to the real conditions of the asset and all available resources to be optimized.
Unlike a traditional relationship where an investor simply allocates capital and delegates execution to third parties, co-investment implies shared commitment. The parties involved are not only connected through a service agreement, but through common exposure to the outcome of the operation. This alignment is particularly important in real estate, where value is rarely created automatically. Value is built through decisions: the entry price, the urban planning framework, the architectural concept, the commercial positioning, cost control, timing and the exit strategy. It also requires the support of excellent tax and legal structuring.
For foreign investors, family offices and funds looking at Portugal as an investment destination, co-investment can represent a balanced alternative between investing independently and relying entirely on external structures. Portugal continues to offer relevant opportunities in markets such as Lisbon, Setúbal, Comporta and the Algarve, but it requires a very precise local reading. The attractiveness of these territories does not remove complexity. On the contrary, in many cases, it is precisely that complexity that creates room for value creation.
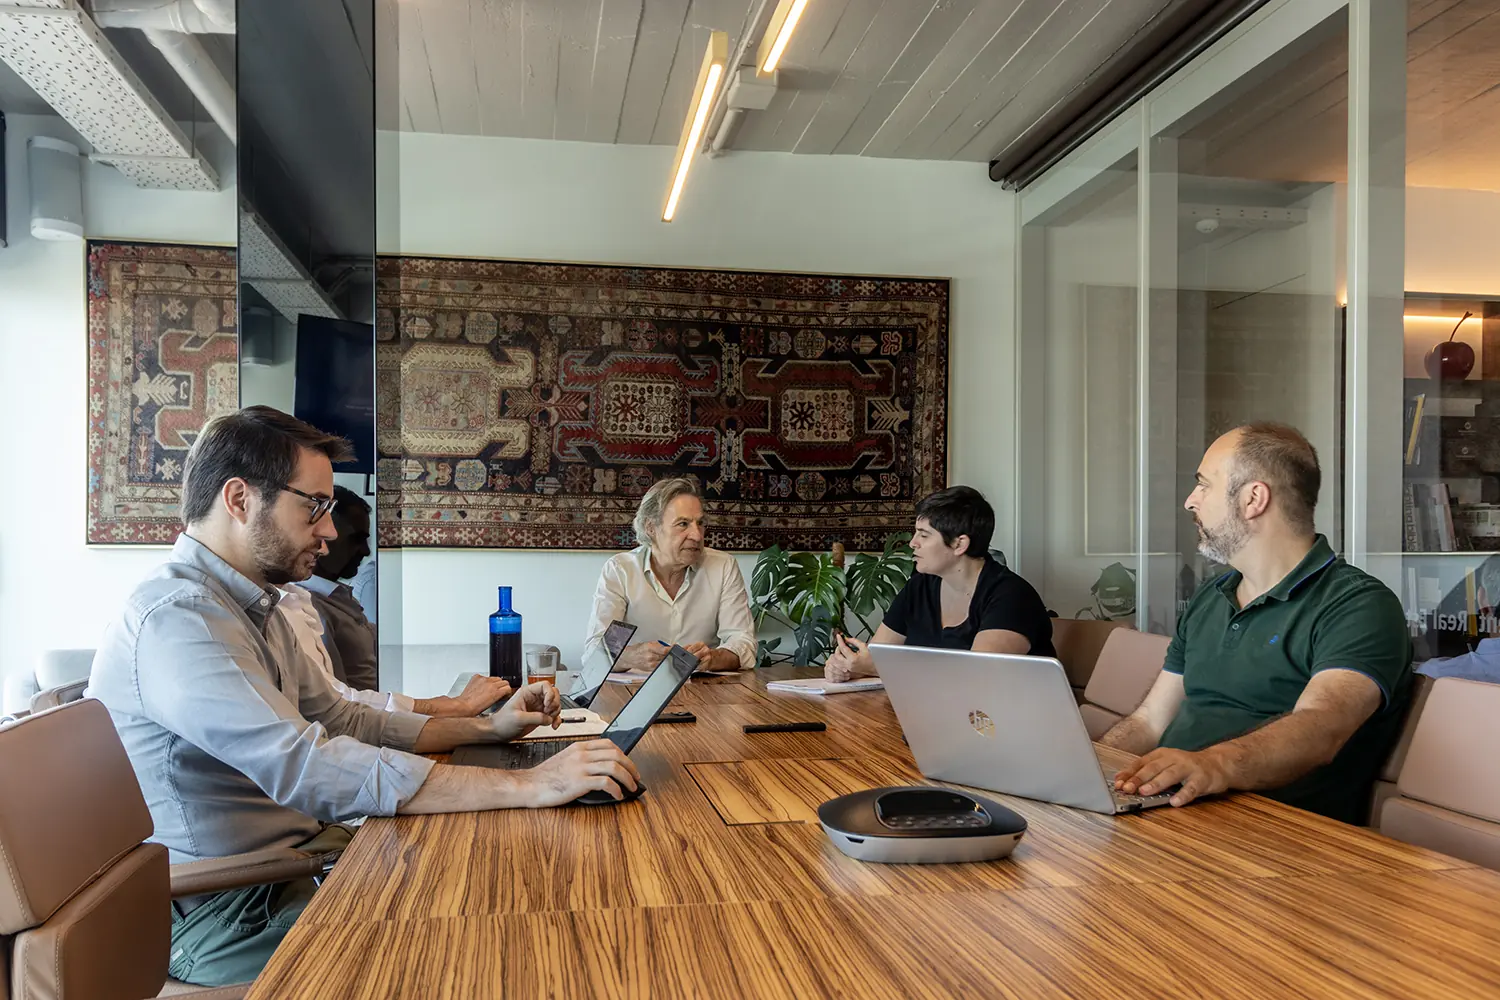
TOTE SER Capital team in a meeting. Photo by TOTE SER Capital
Lisbon, for example, combines liquidity, international demand, scarcity of quality product and significant urban planning pressure. Setúbal presents a different dynamic, with value creation potential linked to urban regeneration, proximity to Lisbon, the waterfront, Arrábida and the evolution of residential and tourism demand. Comporta, in turn, follows a more selective logic, associated with low density, lifestyle, hospitality, nature and premium product. The Algarve combines elements of several of these dynamics. Each market requires its own interpretation. The same strategy does not apply to every asset, and not every asset is suitable for the same type of capital.
One of the main advantages of co-investment is that it allows the investor to access local knowledge without losing direct exposure to value creation. In real estate, understanding a territory and the preferences of its users means much more than knowing prices per square metre. It means understanding who the decision-makers are, what the urban planning constraints may be, what type of product has real demand, which execution risks exist, what costs may arise during construction, which timelines are realistic and which buyers or operators may be present at the exit stage.
This reading is especially relevant in operations involving rehabilitation, urban development, hospitality, premium residential, living, logistics or value-add assets. In these cases, returns do not depend solely on passive market appreciation. They depend on the ability to transform the asset and position it correctly for the right target audience. A vacant building may be merely a problem, or it may become an opportunity. A plot with an undefined planning framework may represent excessive risk, or it may hold significant value creation potential. An underused asset may remain stagnant, or it may be repositioned for more qualified demand. The difference lies in analysis, structure and execution.
Co-investment also helps bring greater discipline to decision-making. When the local partner invests its own capital alongside the investor, the analysis tends to become more rigorous and the investment process more robust. The focus shifts from simply completing a transaction to maximising the overall performance of the operation. The acquisition price is assessed in relation to risk, transformation costs, execution timelines and expected liquidity at exit. This discipline is essential, particularly in markets where the narrative of opportunity can sometimes be stronger than the underlying fundamentals.
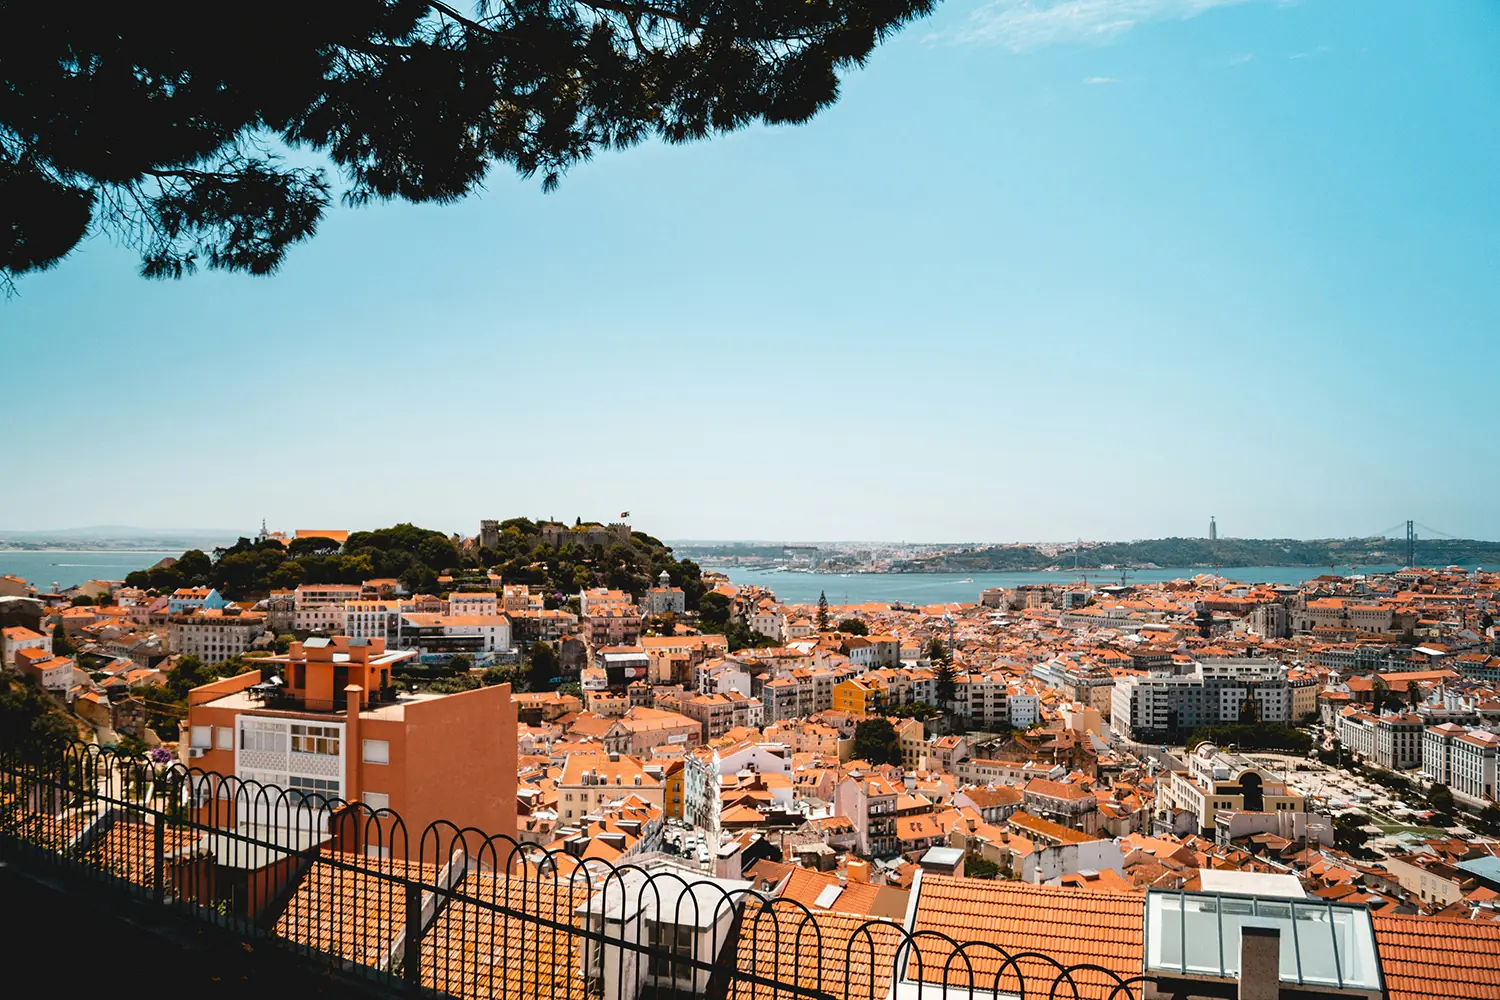
Vista de Lisboa, Portugal. Foto de Louis Droege na Unsplash
Another central point is management. A strong co-investment model, executed by partners with extensive experience, should define from the outset the role of each party: who decides, who executes, who finances, who monitors, who approves relevant changes and how the exit will be carried out. A lack of clarity at this stage can compromise good results. Co-investment should not be informal. It should be structured with clear criteria, responsibilities, control mechanisms, a shared vision of the final objective and the most transparent, effective and appropriate financial vehicle for both the investment and the investors involved.
For owners with capital, co-investment can also be an intelligent way to unlock value. Many real estate assets have potential, but require structure, additional capital, technical capacity or strategic repositioning. Instead of selling prematurely, the owner may partner with investors or operators capable of developing, financing, licensing or transforming the asset, while maintaining exposure to future appreciation. This logic can be particularly relevant for urban buildings, land plots, family-owned assets or properties with underused economic potential.
It is important to note that co-investment does not eliminate risk. No structure does. What it allows is a better distribution and management of that risk. The main risks remain present: acquisition above adjusted value, licensing delays, construction cost overruns, market changes, cost inflation, financing difficulties or lower liquidity at exit. The difference lies in how these risks are analysed before entry and managed throughout the investment cycle.
For this reason, real estate co-investment should be seen less as a financial formula and more as an architecture of alignment. Alignment between capital, local knowledge and proven experience in developed projects. Between strategic vision and technical execution. Between assumed risk and created value. Between ambition and discipline.
In a market such as Portugal, where opportunity exists but is rarely obvious, this approach has become especially relevant. Investing well requires more than identifying assets. It requires interpreting context, structuring decisions and following execution through to the end with experience.
In real estate, true value rarely lies only in the asset itself. It lies in the way the asset is read, transformed and brought to market. When properly designed, co-investment allows precisely that: placing capital, experience and responsibility in the same direction, while also creating the possibility of greater diversification across investments.